Note, 21 October 2026: This series documents our former workflow on one continuous example, the breakout rule over the second 15-minute candle. Its numbers come from our older calculation chain, which books positive results even on a random market without direction (why). On the corrected chain the rule sits significantly below the random market in the DAX, FTSE and Dow, and in the Nasdaq 100 it cannot be told apart from it (re-run). The verdict therefore no longer reads “edge confirmed”. The series stays online as documentation. How we test today: our workflow since October 2026.
Data basis: DAX / FTSE / NQ / Dow M5 + M1, Jan 2018 – Feb 2026, ~2,090 trading days per index. Move logic: to end-of-day or stop-loss (trend tracking). No trading recommendation, no return promise.
This study tests the popular claim that the 2nd 15-minute candle after cash open delivers an especially tradeable trend breakout. The key difference from the pre-market study: the move is not ended at the first opposing candle but tracked to the close — unless the stop-loss (opposite edge, 1R) is hit first. That captures genuine trend days.
| Index | 2nd candle (local) |
|---|---|
| DAX | 09:15–09:30 |
| FTSE 100 | 08:15–08:30 |
| Nasdaq / Dow | 09:45–10:00 NY |
Range & trend-day distribution

| Index | R-med (pts) | ≥ 1R | ≥ 2R | ≥ 3R | ≥ 5R |
|---|---|---|---|---|---|
| DAX | 38.0 | 50.2% | 30.7% | 19.4% | 7.2% |
| FTSE | 15.2 | 50.2% | 30.1% | 16.6% | 6.4% |
| NQ | 48.0 | 50.8% | 28.0% | 14.5% | 4.7% |
| Dow | 82.0 | 51.0% | 28.1% | 16.1% | 4.8% |
About one day in two reaches ≥ 1R. Genuine trend days (≥ 3R) are rarer (14–19%), big trends (≥ 5R) rare (5–7%). DAX and FTSE show the fattest trend tails.
Stop rate vs. trend tail — the trend signature

Because the position is held to the close, the stop rate is high: 57.4% (NQ) to 67.8% (FTSE). That isn't a flaw but the nature of trend trading: many small stops, few large runners. The expectancy comes from the tail, not the hit rate.
Timing — (almost) irrelevant here
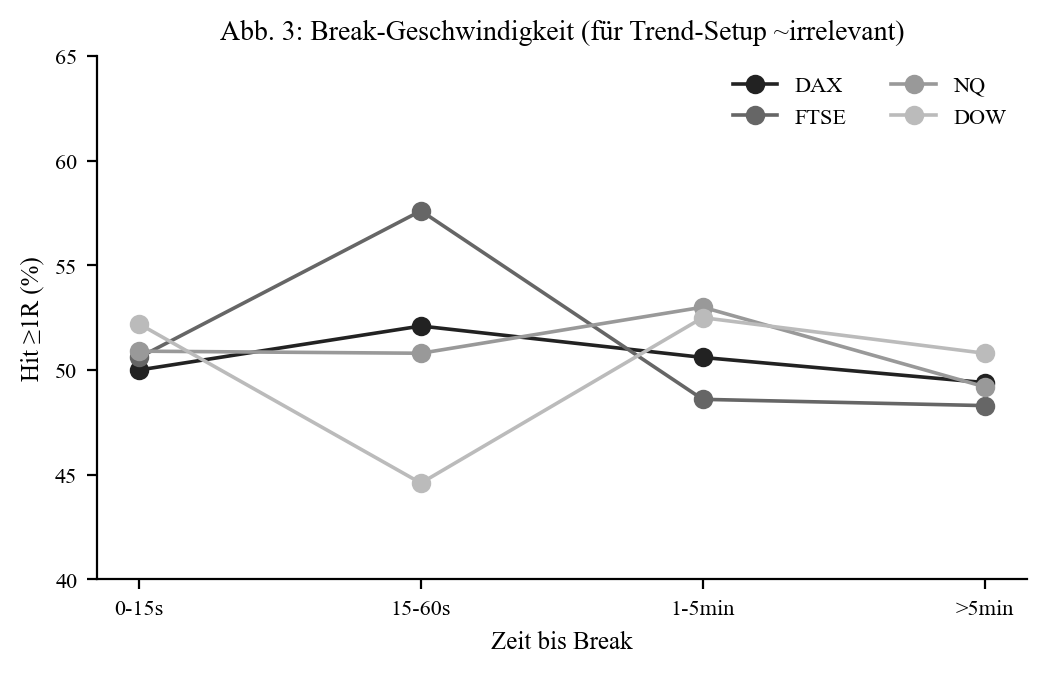
Unlike the pre-market candle, the hit rate is near-constant (~50%) across all timing buckets. When the break happens says little about trend success — plausible, since the trend day develops over hours.
Offset — confirmation pays off (the opposite of the pre-market candle!)
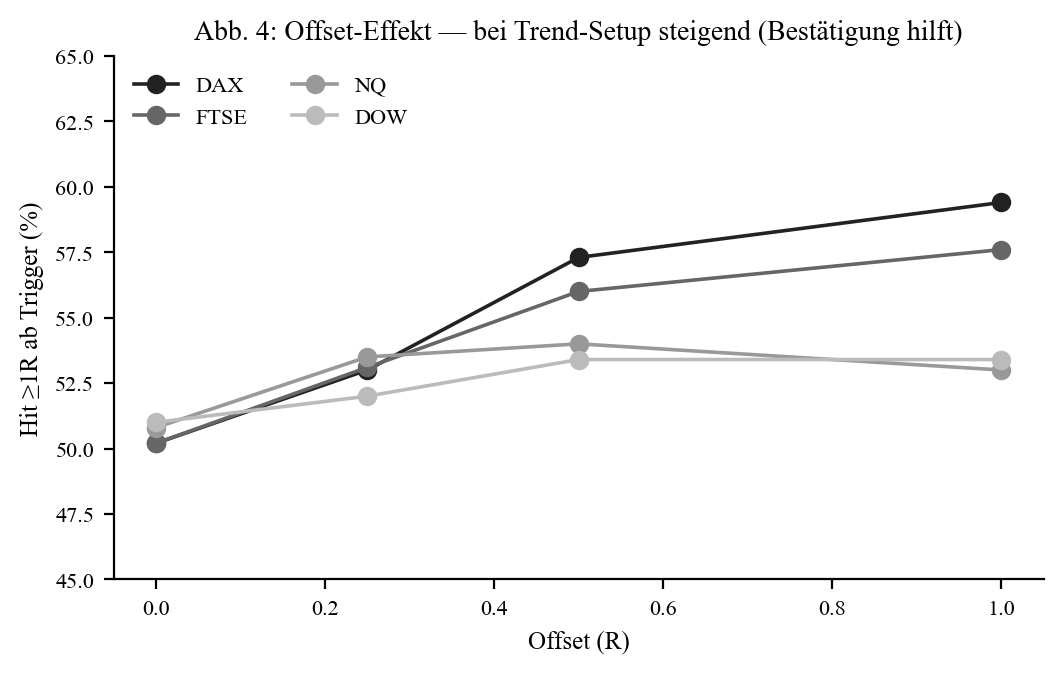
| Index | 0R (immediate) | 0.5R | 1.0R |
|---|---|---|---|
| DAX | 50.2% | 57.3% | 59.4% |
| FTSE | 50.2% | 56.0% | 57.6% |
| NQ | 50.8% | 54.0% | 53.0% |
| Dow | 51.0% | 53.4% | 53.4% |
Perhaps the most important finding: an offset raises the hit rate here (DAX 50.2% → 59.4% at 1R). It filters out the immediate false breaks — waiting for confirmation catches the genuine trend days more often. This is the exact opposite of the pre-market candle, where every offset hurt.
Reversal & Asia/ONR sweep

After a failed break the opposite side almost always breaks (~90–97%), but reaches 1R in only 44–51% of cases — 19–24% across all days. The reversal stays the weaker side.

Neither the Asia nor the ONR edge acts as a reversal level: when the trend move reaches the level, it breaks through in ~75–85% of cases. For a trend setup that's even expected — and matches the DAX pre-market study.
Pre-market candle vs. 2nd candle (DAX) — complementary
| Metric | Pre-market candle | 2nd opening candle |
|---|---|---|
| Move logic | to opposing candle/SL | to EOD/SL (trend) |
| Hit ≥ 1R | 56.8% | 50.2% |
| Hit ≥ 5R | 4.3% | 7.2% |
| SL hit rate | 37.2% | 64.9% |
| Break-speed effect | strong | weak |
| Offset effect | lowers hit rate | raises hit rate |
The two setups are complementary: the pre-market candle is an impulse setup (higher hit rate), the 2nd candle a trend setup (fatter tail). Above all the offset effect flips — confirmation hurts the impulse, helps the trend.
Profit factor and spread sensitivity

So far only the reach in R was considered — spread-independent. For a tradeable assessment the spread must be included as a fixed point cost. We test a simple fixed-TP rule (take-profit at 1R resp. 2R, stop-loss at 1R) at round-trip spreads of 0 / 0.5 / 1 / 2 points.
Spread as a fraction of R (a fixed spread hits tight markets harder):
| Spread | DAX (R≈38) | FTSE (R≈15) | NQ (R≈48) | Dow (R≈82) |
|---|---|---|---|---|
| 0.5 pt | 1.3% | 3.3% | 1.0% | 0.6% |
| 1.0 pt | 2.6% | 6.6% | 2.1% | 1.2% |
| 2.0 pt | 5.3% | 13.2% | 4.2% | 2.4% |
Profit factor of the fixed TP-1R rule:
| Spread | DAX | FTSE | NQ | Dow |
|---|---|---|---|---|
| 0.0 | 1.01 | 1.01 | 1.03 | 1.04 |
| 0.5 | 0.98 | 0.94 | 1.00 | 1.03 |
| 1.0 | 0.95 | 0.87 | 0.98 | 1.01 |
| 2.0 | 0.89 | 0.76 | 0.92 | 0.98 |
Key finding: the fixed-TP rule is only marginally profitable even at zero spread (PF ~1.0) and clearly drops below with spread — most for the FTSE (small R, spread eats 3–13% of R). TP-2R is consistently worse (PF 0.7–0.9). This is not a contradiction but the logical consequence of the trend nature: fixed take-profits cut exactly the fat tail that carries the expectancy. This setup's value lies not in fixed targets but in letting winners run — exactly the exit-logic study finding. Unlike the pre-market candle (impulse setup, TP-1R PF up to 2.5), the 2nd candle is not suited to fixed TPs.
Characteristics of the 2nd candle: inside bar, colour, ONR position
Does the nature of the 2nd candle itself change the expectancy of the break trade? Three characteristics, tested cross-asset across all four indices, measured on realised net-R (Time-BE-60, net of spread):
Inside bar (2nd candle fully inside the 1st): no adverse effect — contrary to the obvious intuition. Cross-asset +0.13 R (inside) vs +0.11 R (non-inside), mixed per index (NQ/DOW slightly better inside, DAX/FTSE slightly worse). An inside bar is therefore not negative — it just gives a smaller R; the per-R outcome is essentially the same. No usable filter signal.
Colour of the 2nd candle (bullish vs bearish): completely irrelevant. Bullish +0.11 R vs bearish +0.11 R cross-asset — and contradictory per index (DAX likes bullish, DOW bearish). Pure noise.
Close relative to the overnight range (ONR) × break direction: here there is real structure.

| Close of the 2nd candle | Break ↑ (long) | Break ↓ (short) |
|---|---|---|
| above ONR | +0.16 | +0.22 |
| inside ONR | +0.06 | +0.15 |
| below ONR | −0.07 | +0.13 |
(cross-asset expectancy in net-R per trade)
Key findings:
- Short beats long in every ONR bucket (cross-asset) — confirms the series' short tendency (consistent on NQ/FTSE/DOW; DAX neutral).
- Best setup: close above the ONR, then break down (+0.22 cross; NQ +0.36, DAX +0.34, DOW +0.21) — a reversal short after overnight strength. The strongest, most consistent positive signal.
- Only negative bucket: close below the ONR, then break up (−0.07 cross; NQ/FTSE −0.18) — a long against overnight weakness. Caveat: mildly positive on DAX/DOW, so a tendency, not a hard rule.
Overnight gap (today's open vs yesterday's close) × break direction: the same pattern, even clearer.

| Break ↑ (long) | Break ↓ (short) | |
|---|---|---|
| Gap up | +0.07 | +0.21 |
| Gap down | +0.08 | +0.13 |
(cross-asset expectancy in net-R per trade)
Key finding: "gap up → break down" (gap-fade short) is the strongest setup (+0.21) — and the only one positive on all four indices (NQ/DOW +0.31, DAX +0.17, FTSE +0.05). Short beats long in both gap regimes. A gap down, by contrast, produces no strong directional edge (both sides ~+0.08…+0.13). This matches the ONR finding exactly: the highest expectancy is in shorting morning strength (close above ONR, or gap up → break down).
Honestly framed: ONR position and gap carry signal (gap-fade short is even 4/4-consistent), but with cross-index variance — and every extra condition is a parameter and thus an overfit risk. How to incorporate such features into an algorithm at all — and why a risk/size adjustment (conviction sizing) is usually more robust than a hard filter — is covered in the methodology. Inside bar and candle colour, by contrast, are clear null results.
Conclusion
The 2nd opening candle is partly a trend breakout — with clear asymmetry: no high hit rate (~50%, stop 57–68%), but fat tails (≥ 3R on 16–19%, ≥ 5R on 5–7%). Whoever endures the many stops catches the few large trend days. Consistent across all four indices.
Limitations: trend logic to EOD/SL (other exits → other numbers); spread is modelled (see spread section), but slippage is not; single-source data; news events/volume not covered.
📄 Full study as PDF · See also: 7th opening candle
Disclaimer: Historical statistics are no guarantee of future market behaviour. Not investment advice. Trading involves risk of loss up to total loss.